A Pag-IBIG housing loan is how most first-time Filipino buyers finance a condo or a house and lot. The process is simpler than it looks once you know two things: whether you qualify, and which documents to prepare. This checklist covers both, plus how much you can borrow in 2026.
Quick answer: To get a Pag-IBIG housing loan in 2026, you need 24 monthly contributions, must be 65 or younger when you apply (with the loan paid off by 70), and need a clean Pag-IBIG housing record. You prepare the application form, proof of income and a valid ID. The developer or seller usually provides the title, vicinity map and tax declaration.
Who qualifies for a Pag-IBIG housing loan?
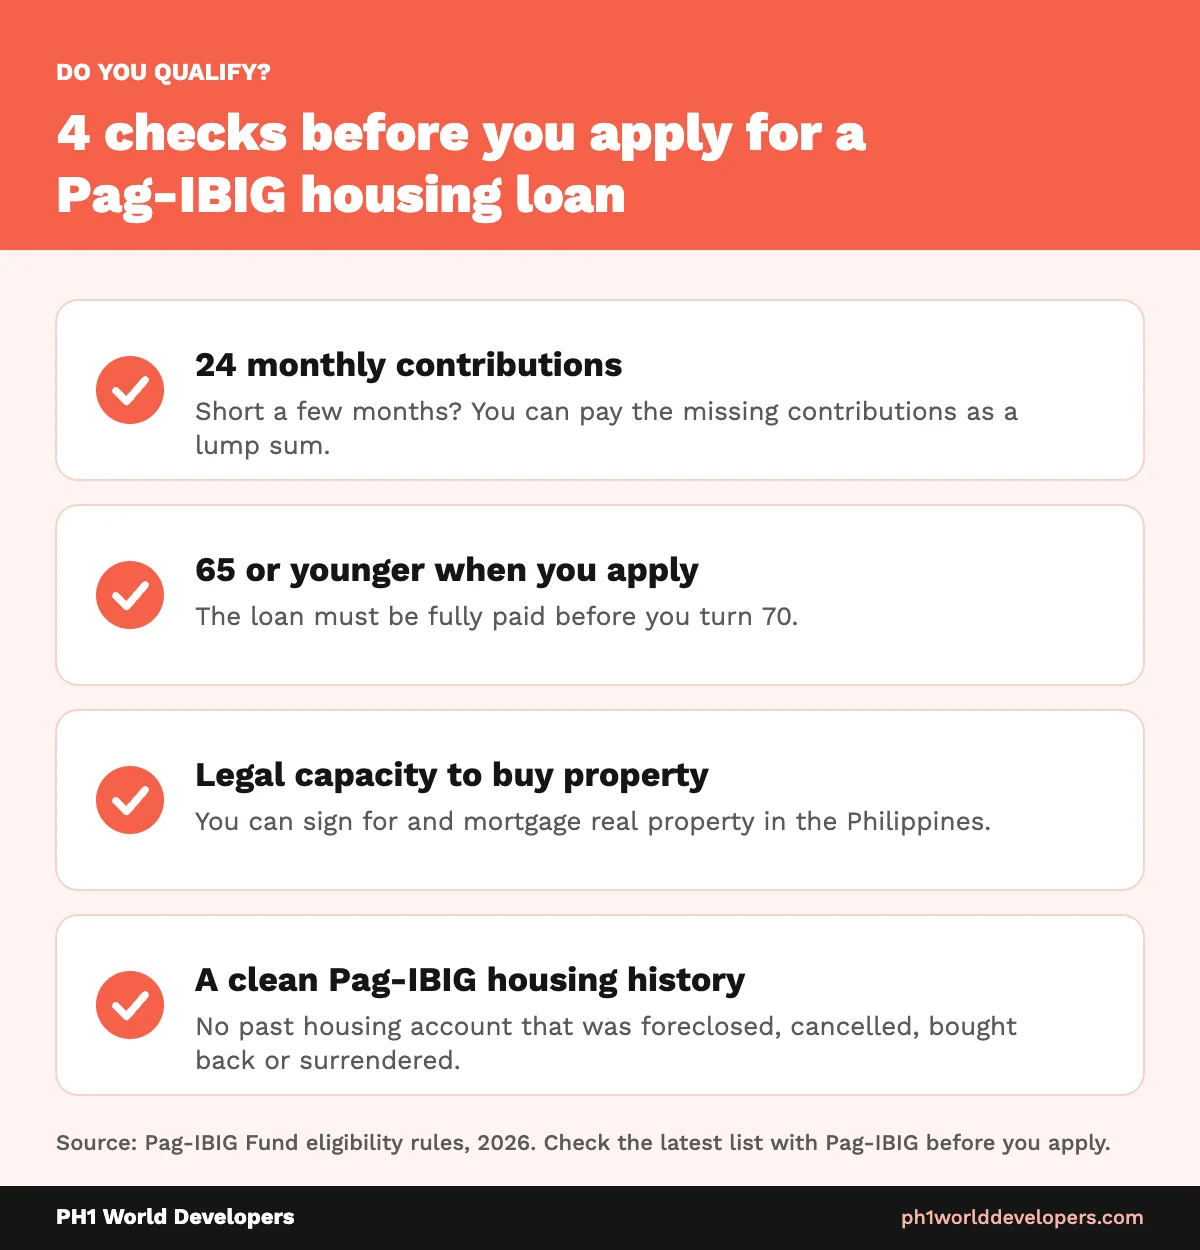
To qualify for a Pag-IBIG housing loan, you need at least 24 monthly contributions, must be no older than 65 when you apply, and must have the loan fully paid before you turn 70. You also need the legal capacity to acquire and mortgage real property in the Philippines.
Pag-IBIG also checks your history with the Fund. A previous Pag-IBIG housing account that was foreclosed, cancelled, bought back or surrendered can disqualify you.
How much can you borrow from Pag-IBIG in 2026?
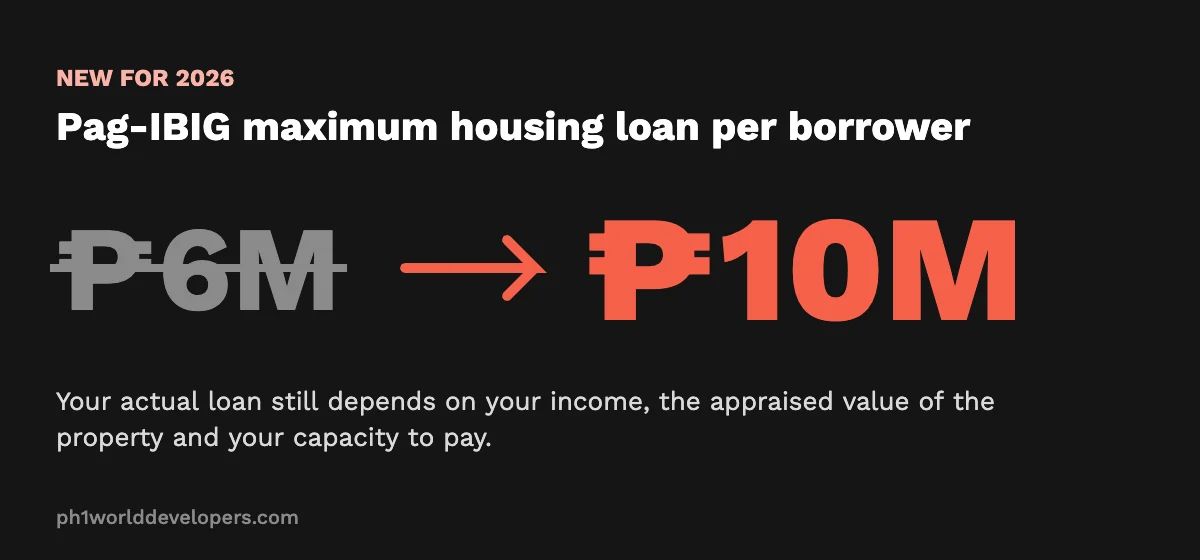
Pag-IBIG raised its maximum housing loan from ₱6 million to ₱10 million per borrower in 2026. The amount you actually receive depends on your income, the appraised value of the property, and your capacity to pay.
The higher ceiling matters for mid-market condos. Units that previously needed a bank loan or a large cash top-up may now fit within Pag-IBIG financing.
What documents do you need for a Pag-IBIG housing loan?
You’ll prepare the personal documents; the property documents are usually coordinated with the seller or developer. Use this table as your checklist.
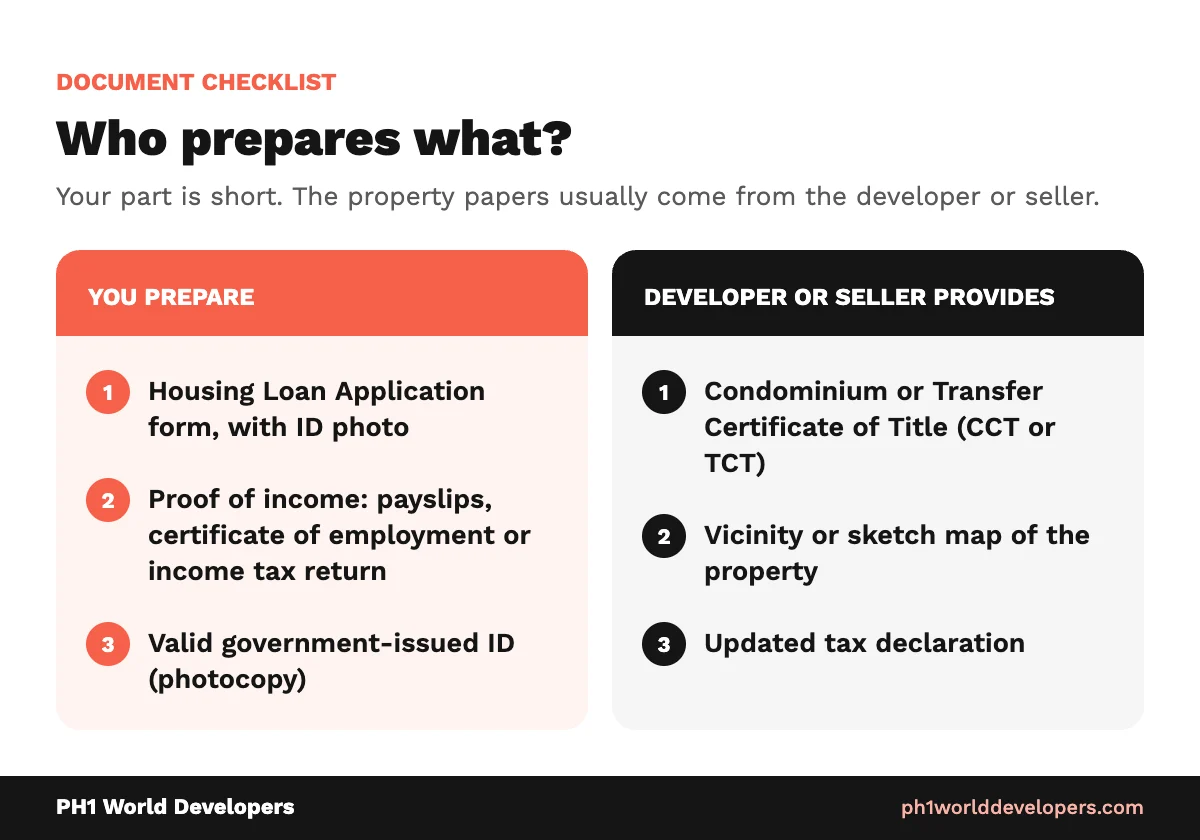
| Document | Who usually provides it |
|---|---|
| Housing Loan Application form, with ID photo | You |
| Proof of income (payslips, certificate of employment, or income tax return) | You |
| Valid government-issued ID (photocopy) | You |
| Condominium or Transfer Certificate of Title (CCT or TCT) | Developer or seller |
| Vicinity or sketch map of the property | Developer or seller |
| Updated tax declaration | Developer or seller |
Pag-IBIG may ask for more documents depending on your situation, so check the latest list at the branch or on Pag-IBIG’s official channels before you submit.
What if you’re self-employed or an OFW?
The eligibility rules are the same. What changes is how you prove income: self-employed buyers usually submit income tax returns and business documents instead of payslips, while OFWs submit proof of overseas employment and income.
If you’re an OFW buying a socialized unit under the government’s Expanded 4PH program, eligibility is broader. See our guide to the 4PH program requirements.
How do you avoid delays in your Pag-IBIG application?
The most common cause of delay is an incomplete or outdated document. Submit everything at once and keep a copy of every page.
- Make sure the name on every document matches your Pag-IBIG record exactly.
- Use recent payslips and a certificate of employment dated within the period Pag-IBIG requires.
- Pay any missing contributions before you apply so you meet the 24-month requirement.
- Ask the developer early when the property documents will be ready.
Pag-IBIG or bank loan: which should you use?
Pag-IBIG is often the better fit for first-time buyers because it is built for its members and offers long repayment terms. Banks can move faster for buyers with strong credit and larger loans. Compare the monthly amortization, the repricing period and total fees side by side before choosing.
Frequently asked questions
Can I apply for a Pag-IBIG loan with fewer than 24 contributions?
You can pay the remaining contributions as a lump sum to meet the 24-month requirement.
What is the maximum Pag-IBIG housing loan in 2026?
₱10 million per borrower, up from ₱6 million. Your actual loan depends on income, property value and capacity to pay.
Is there an age limit for a Pag-IBIG housing loan?
Yes. You must be 65 or younger when you apply, and the loan must mature by age 70.
Can I use a Pag-IBIG loan for a pre-selling condo?
Pag-IBIG financing is usually released when the unit is ready for turnover. During construction, you pay the developer’s down payment. Ask the developer how their payment schedule works with Pag-IBIG.
Found a home you can finance? Browse PH1 World Developers’ properties and ask which financing options apply to the project you like. Browse PH1 properties