Before you reserve a condo or a house and lot, you should know one number: your monthly amortization. A Pag-IBIG loan calculator gives you that number in seconds, but only if you know what to type in and what the result leaves out. This guide walks you through the inputs, shows two worked examples, and lists the costs a calculator won’t show you.
Quick answer: Your Pag-IBIG monthly amortization comes from three numbers: the loan amount, the interest rate for your repricing period, and the loan term (up to 30 years). A longer term lowers the monthly payment but raises the total interest. A calculator covers principal and interest only, so budget separately for fees, insurance and association dues.
Pag-IBIG monthly amortization calculator
Estimate only. Covers principal and interest, not insurance, fees or association dues. Enter the rate Pag-IBIG publishes for your repricing period. The income estimate assumes your amortization stays within about 35% of gross monthly income. For an official figure, use Pag-IBIG’s Housing Loan Affordability Calculator.
How is Pag-IBIG monthly amortization computed?
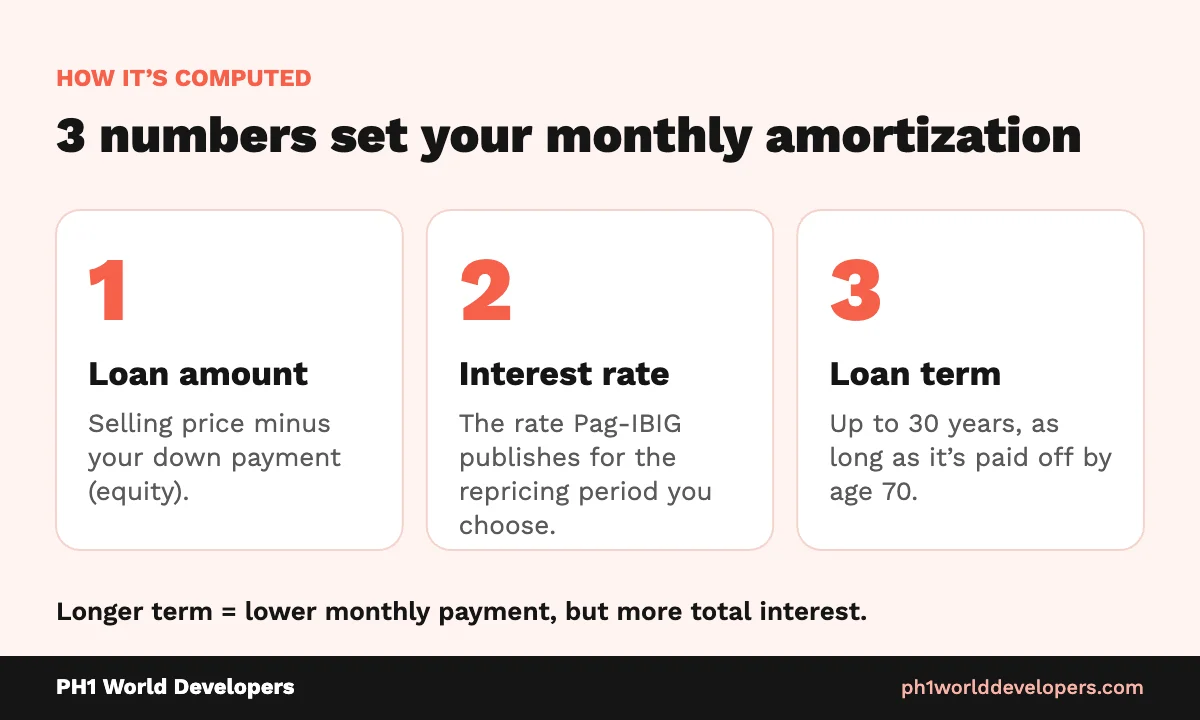
Your monthly amortization comes from three numbers: the loan amount, the interest rate, and the loan term. A longer term lowers your monthly payment but increases the total interest you pay over the life of the loan.
Every Pag-IBIG loan calculator uses the same standard amortization formula that banks use. Once you know the three inputs, you can check any quote you receive.
What do you need before using a Pag-IBIG loan calculator?
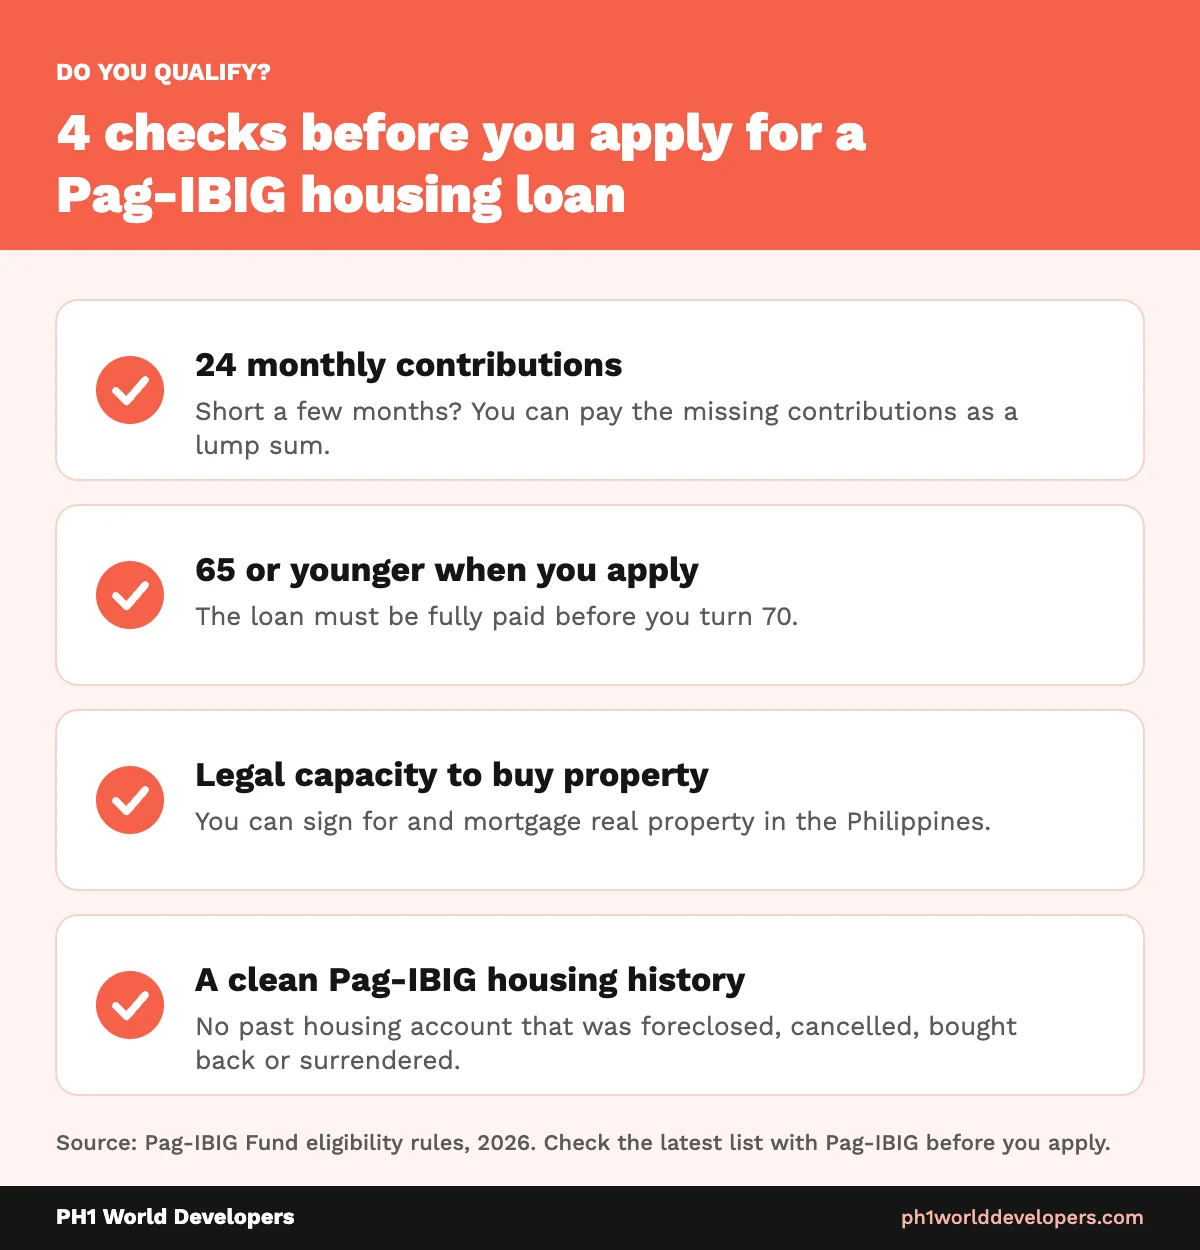
You need the loan amount (the selling price minus your down payment), the interest rate for the repricing period you choose, and the loan term in years. Pag-IBIG housing loans can run for up to 30 years, as long as the loan is fully paid by the time you turn 70.
- Loan amount: ask the developer for the total contract price and the required equity or down payment. The loan covers what’s left.
- Interest rate: Pag-IBIG publishes its current rates for each fixed-rate (repricing) period. Use the published rate, not an estimate from a social media post. Pag-IBIG’s official Housing Loan Affordability Calculator also shows how much you can borrow.
- Loan term: choose between shorter terms (higher monthly payment, less total interest) and longer terms (lower monthly payment, more total interest).
What does a real 4PH example look like?
Under the government’s Expanded 4PH program, eligible buyers can get a subsidized interest rate while the promo is offered. For a real example, see Avesta Residences, PH1 World Developers’ own 4PH project, and ask our team for a sample computation at the current promo rate.
What does a mid-market condo example look like?
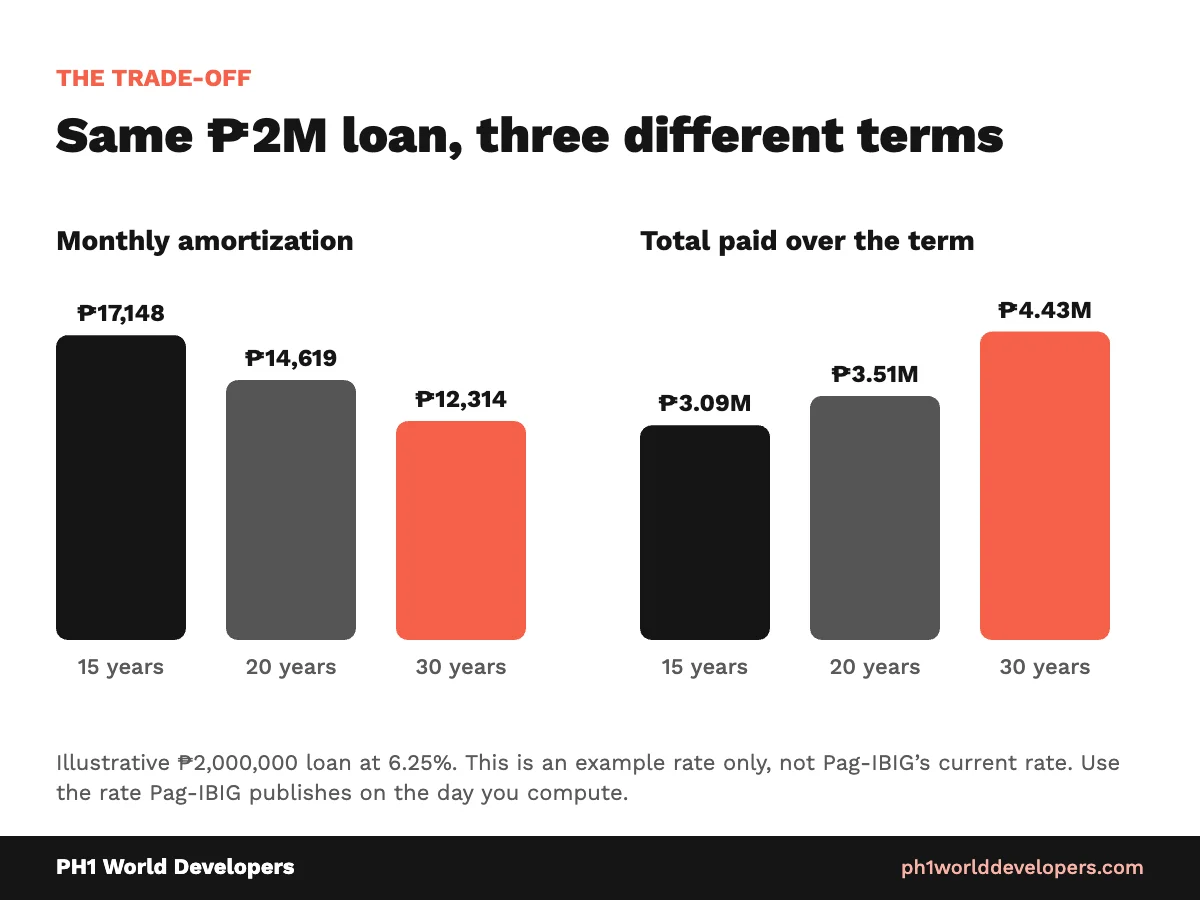
Here is an illustrative ₱2,000,000 loan. The 6.25% interest rate is an example only and is not Pag-IBIG’s current rate, so replace it with the rate Pag-IBIG publishes on the day you compute.
| Loan term | Monthly amortization | Total paid over the term |
|---|---|---|
| 15 years | ₱17,148 | ₱3,086,722 |
| 20 years | ₱14,619 | ₱3,508,455 |
| 30 years | ₱12,314 | ₱4,433,164 |
The trade-off is clear in the numbers: moving from a 15-year to a 30-year term cuts the monthly payment by almost ₱5,000, but adds more than ₱1.3 million to what you pay in total.
How much monthly amortization can you afford?
Choose a monthly payment you could still make in a difficult month, not just in a good one. Pag-IBIG assesses your capacity to pay from your income documents, so an amortization that strains your budget can also reduce the loan amount you’re approved for.
A practical test: subtract the amortization from your monthly take-home pay, then check that what remains still covers food, transport, utilities, tuition and savings. If it doesn’t, look at a longer term, a bigger down payment, or a lower-priced unit.
What costs does a loan calculator leave out?
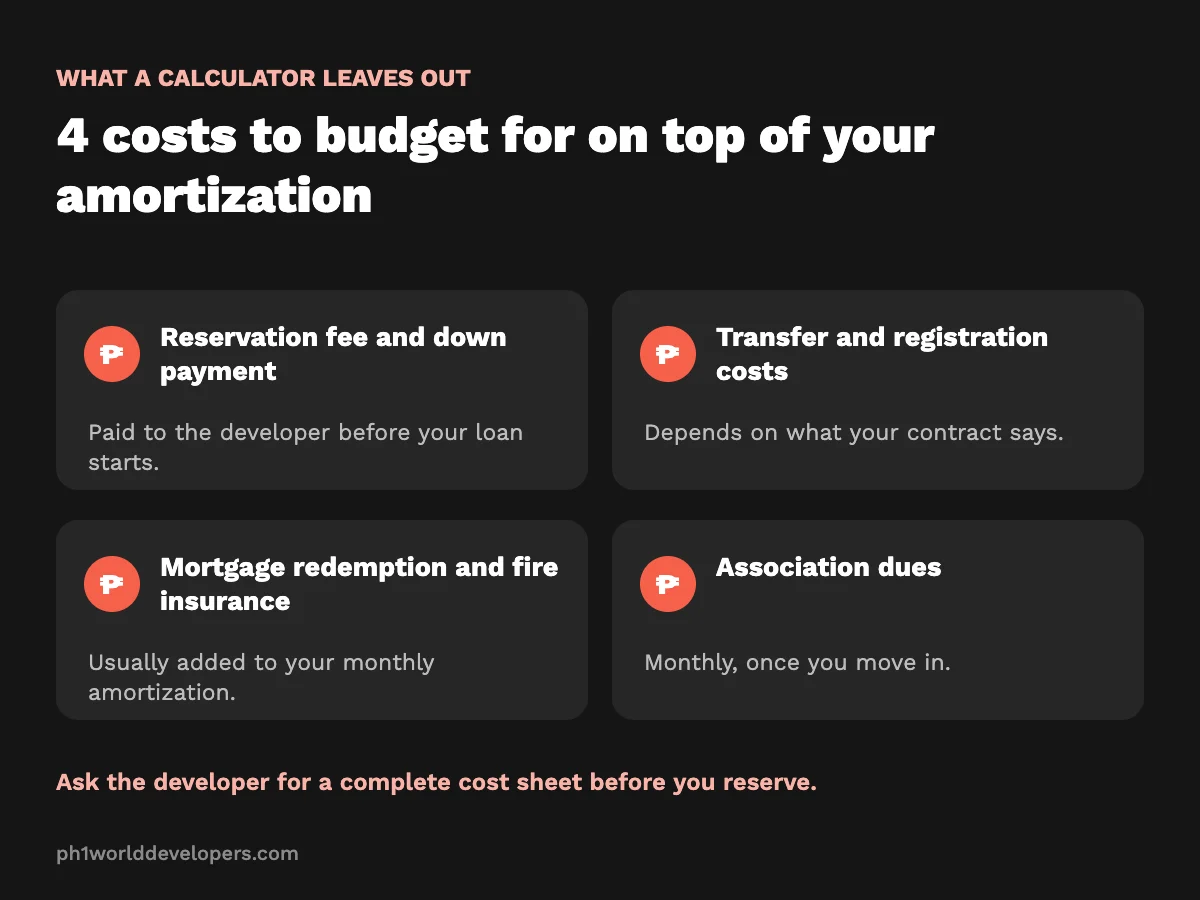
A calculator shows principal and interest only. Budget separately for these costs, because they are where first-time buyers are most often surprised:
- Reservation fee and down payment (equity) paid to the developer
- Transfer and registration costs, depending on what your contract says
- Mortgage redemption and fire insurance, usually added to the monthly amortization
- Monthly association dues once you move in
Ask the developer for a complete cost sheet before you reserve, and add those amounts to your monthly budget.
What happens when your rate is repriced?
Pag-IBIG rates are fixed for the repricing period you choose and then adjusted. If rates are higher at repricing, your monthly amortization goes up. Test your budget at a rate one or two percentage points higher than today’s so a repricing doesn’t catch you off guard.
If you ever fall behind on installments paid directly to a developer, the Maceda Law sets out your grace periods and refund rights.
Frequently asked questions
It is accurate for principal and interest, based on the inputs you enter. It does not include insurance, fees or association dues.
Up to 30 years, provided the loan matures before you reach age 70.
No. It applies only to eligible socialized housing units under the Expanded 4PH program, and only while the promo rate is offered. Check the program requirements to see if you qualify.
Only if you need the lower payment. A longer term reduces the monthly amount but increases the total interest you pay.
Using an example rate of 6.25% (not Pag-IBIG’s current rate), a ₱2,000,000 loan comes to about ₱17,148 a month over 15 years, ₱14,619 over 20 years, or ₱12,314 over 30 years. Use the rate Pag-IBIG publishes on the day you compute to get your own number.
Ready to run real numbers? Browse PH1 World Developers’ properties, ask for a unit’s price and payment terms, and compute your amortization before you reserve. Browse PH1 properties
Sources
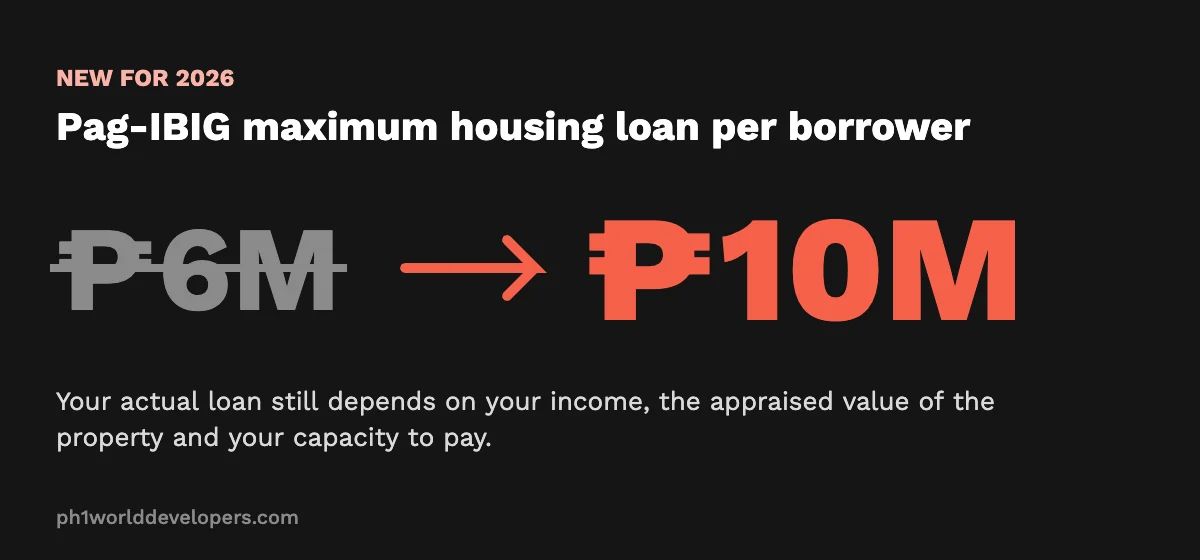
- JournalNews, Pag-IBIG maximum loan increase and 4PH amortization example (2026)
- FDCP National Registry, Pag-IBIG Fund housing loan overview (loan term up to 30 years)
- Inquirer Plus, Pag-IBIG housing loan eligibility (age limits)
- Philstar, Pag-IBIG Fund raises limit on housing loans to P10 million (May 2026)